DSCR Loans for Properties With an ADU: What to Know
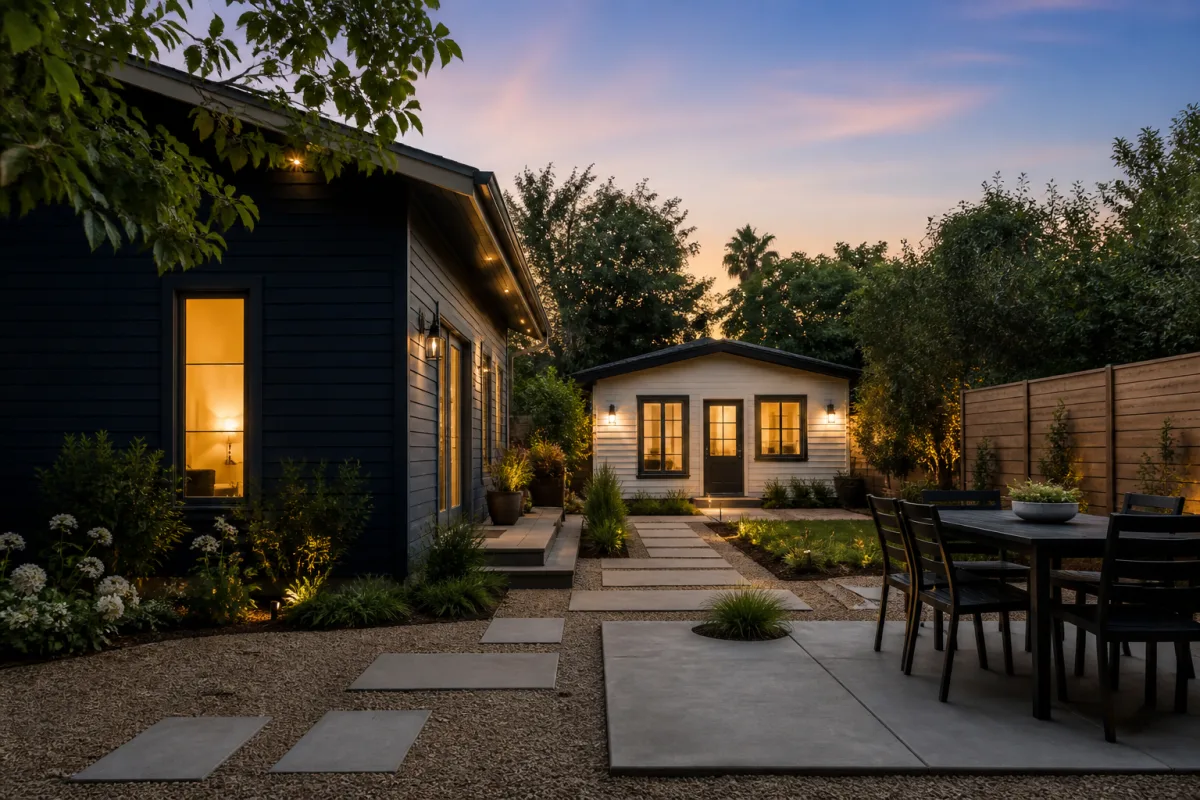
Accessory dwelling units have become an increasingly common feature on investment properties as more jurisdictions relax zoning restrictions to encourage additional housing supply. For DSCR qualification purposes, an ADU raises a specific question worth understanding before you count on it: can the additional unit’s rental income actually be included in your ratio, and does the answer depend on the ADU’s permit status?
Permitted ADUs Are the More Straightforward Case
When an ADU is legally permitted and reflected as such in local zoning and property records, most DSCR programs will include its rental income in the overall property income used for qualification — treated similarly to any additional legal rental unit on the property, whether that’s a duplex’s second unit or a basement apartment.
Total Property Income = Main Unit Rent + ADU Rent
DSCR = Total Property Income ÷ PITIA
The appraisal for an ADU-included property typically documents the additional unit’s market rent as part of the overall rent schedule, giving underwriting a documented basis for including that income.
Unpermitted ADUs Are Where It Gets More Restrictive
An ADU that exists physically but isn’t reflected in permitted zoning or building records creates real underwriting caution, for a few overlapping reasons: appraisers are generally cautious about assigning value or rent credit to unpermitted structures, some programs won’t count unpermitted rental income toward DSCR qualification at all, and there’s a practical risk that local code enforcement could require the unit to be modified or removed, which would directly eliminate the income the loan was qualified against.
If a property you’re considering has an ADU of uncertain permit status, it’s worth researching the local jurisdiction’s specific rules — some areas have retroactive permitting or amnesty programs for older unpermitted units, which could resolve the issue before you close, but this varies significantly by city and county.
What to Verify Before Counting on ADU Income
- Confirm permit status directly with the local building/zoning department, rather than relying solely on what a seller or listing states.
- Check whether the ADU is reflected on the property’s tax records as an additional unit, which is often a useful (though not definitive) signal of permitted status.
- Ask whether the specific program you’re considering has a defined policy for unpermitted ADU income — some may allow a conservative, reduced credit even without full permitting, while others exclude it entirely.
- Get the appraiser’s rent schedule reviewed carefully to see exactly how (or whether) the ADU’s income was included in the total.
Converting an Unpermitted ADU After Purchase
If you’re purchasing a property with an existing unpermitted ADU and planning to formalize its permit status after closing, understand that the loan will likely be qualified without that income until the permit status changes — plan your initial cash flow assumptions around the property without the ADU income, and treat any future permitted-status income as an upside once achieved, not something to count on for the initial approval.
A Practical Approach
Treat ADU rental income as a genuine value-add worth pursuing, but verify permit status early in your due diligence rather than assuming it will simply be included once you’re deep into the underwriting process — a permit status surprise late in the process can affect your approved loan amount if the qualifying income changes.
Exploring DSCR financing for a property with an ADU? Submit a confidential inquiry or call (907) 841-1600.
Frequently Asked Questions
Can I count ADU rental income toward my DSCR ratio if it’s not yet permitted?
This varies by program — some exclude unpermitted income entirely, others may allow limited or conservative credit; confirm the specific policy before counting on that income for qualification.
How do appraisers handle ADUs in their rent schedule?
For permitted ADUs, appraisers typically document market rent for the additional unit as part of the overall income opinion; for unpermitted units, appraisers are generally more cautious and may exclude or heavily qualify any rent estimate.
Does an ADU increase the overall value of an investment property?
Often yes, since it adds usable rental square footage and income potential, though the value contribution depends significantly on permit status, quality of construction, and local market demand for multi-unit configurations.
What if I want to build a new ADU after purchasing the property?
This is generally a separate project from the initial loan qualification — the loan would be based on the property’s current income, and any future ADU income would need to be documented and potentially refinanced or reassessed once built and rented.
Are ADU permitting rules the same across every jurisdiction?
No — ADU zoning, permitting requirements, and any amnesty programs for existing unpermitted units vary significantly by city and county, so local verification is essential rather than assuming a blanket national rule.
Have a property in mind?
Submit a confidential inquiry — business-purpose and investment property only.
Start InquiryDisclaimer: This article is for informational purposes only and does not constitute financial, lending, legal, or tax advice. Commercial & DSCR Loans is a marketing and referral information service — not a lender, broker, or financial institution. Content relates to business-purpose and investment property financing only. Disclaimer · Terms · Privacy