Property Condition Escrows on DSCR Loan Purchases
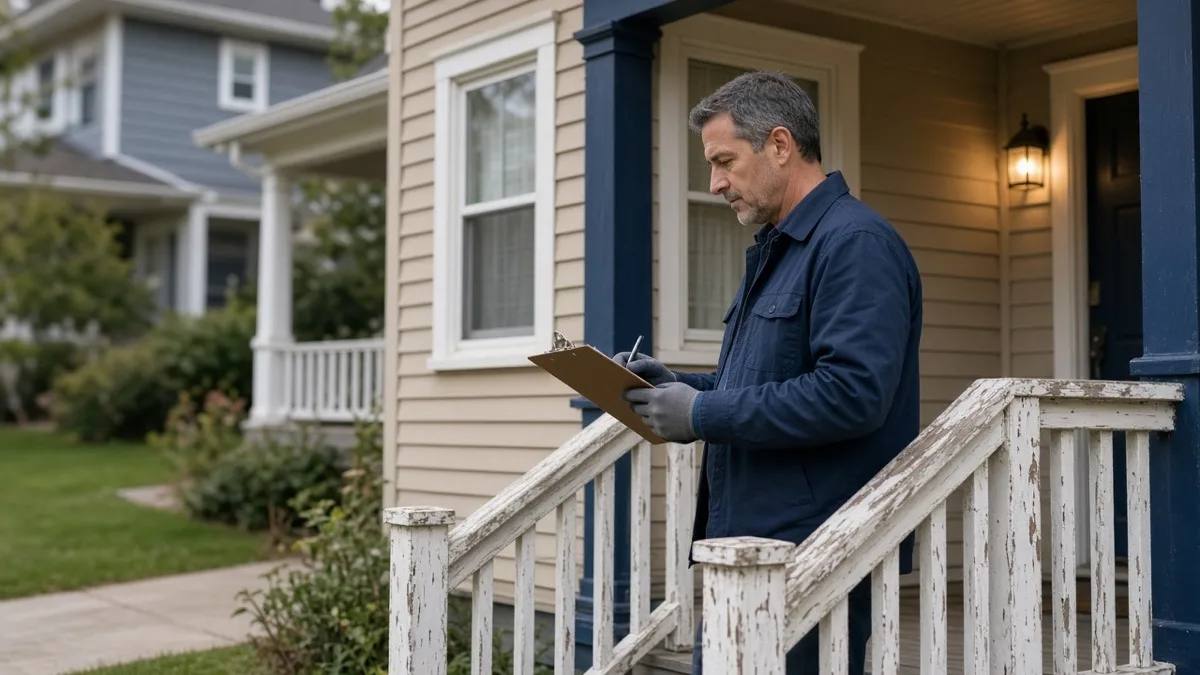
Not every investment property is turnkey at purchase. When an appraisal or inspection flags specific deferred maintenance items — an aging roof nearing the end of its useful life, deferred exterior repairs, safety issues — a DSCR lender may require a repair escrow holdback as a condition of closing, rather than declining the loan outright or requiring repairs before close.
What a Repair Escrow Holdback Actually Is
Rather than requiring the seller or buyer to complete repairs before closing (which can create timing conflicts, especially with a motivated seller or a competitive purchase), some lenders instead hold back a portion of loan proceeds in an escrow account, released once the required repairs are completed and verified, typically through a follow-up inspection. This lets the transaction close on schedule while still ensuring the property condition issue gets addressed within an agreed timeframe.
What Typically Triggers a Holdback Requirement
- Health and safety items flagged in an appraisal or inspection, such as exposed wiring, non-functional smoke detectors, or structural concerns, are the most common trigger and often the least negotiable.
- Roof condition nearing or past its expected useful life, particularly if an appraiser notes visible wear or the roof is beyond a certain age threshold for the specific roofing material.
- Deferred exterior maintenance that could accelerate into a larger issue if left unaddressed, such as peeling paint exposing bare wood siding in a wet climate.
- Pest or wood-destroying organism findings from an inspection, particularly in regions where termite or moisture damage is a known regional risk factor.
How Much Gets Held Back and For How Long
The specific holdback amount is typically based on a contractor estimate or the appraiser’s repair cost assessment, often with some cushion added, and the timeframe to complete repairs is usually set at closing, commonly ranging from 30 to 180 days depending on the scope of work and the specific lender’s policy. Missing the completion deadline can have consequences ranging from an extension request to, in more serious cases, technical default provisions, so it’s worth being realistic about repair timelines rather than assuming the shortest possible estimate.
Planning for This Before You Make an Offer
If you’re purchasing a property you already suspect has deferred maintenance — an older roof, visible exterior wear, or known regional risk factors like termites — budgeting for a potential repair escrow requirement before you submit an offer helps avoid a late-stage surprise that could affect your total cash-to-close. Getting a preliminary sense of likely repair items from your own inspection, before the lender’s appraisal comes back, can help you negotiate seller concessions or adjust your offer price proactively rather than reactively.
Who Actually Completes the Repairs
Depending on the lender’s requirements, repairs may need to be completed by a licensed contractor with proof of work (invoices, before/after documentation, sometimes a re-inspection), rather than DIY work, particularly for safety-related items. Confirm this requirement upfront, since assuming you can complete repairs yourself when the lender requires licensed contractor documentation can create delays in releasing the escrowed funds.
Frequently Asked Questions
Does a repair escrow holdback delay my closing?
Not typically — the point of a holdback is specifically to allow closing to proceed on schedule while repairs are completed afterward, rather than requiring completion before close.
What happens if I don’t complete the repairs within the required timeframe?
This varies by lender, but consequences can range from an extension request (sometimes with additional documentation) to more serious default-related provisions in more severe cases — check your specific loan documents for the exact terms.
Can the seller be required to pay for the repair escrow instead of me?
This is a negotiation point in the purchase contract, separate from the loan requirement itself — some buyers negotiate seller credits or repair completion as part of the purchase agreement to offset this cost.
Are repair escrows common on DSCR loans, or rare?
They come up regularly, particularly on older or value-add-oriented investment properties, though not every purchase triggers one — it depends specifically on what the appraisal and inspection flag.
Do I earn interest on funds held in a repair escrow account?
This varies by lender and account structure — ask specifically about your loan’s escrow account terms rather than assuming a standard answer applies.
Exploring DSCR financing for an investment rental? Submit a confidential inquiry or call (907) 841-1600.
Have a property in mind?
Submit a confidential inquiry — business-purpose and investment property only.
Start InquiryDisclaimer: This article is for informational purposes only and does not constitute financial, lending, legal, or tax advice. Commercial & DSCR Loans is a marketing and referral information service — not a lender, broker, or financial institution. Content relates to business-purpose and investment property financing only. Disclaimer · Terms · Privacy